
A credit card sitting in your wallet is not the problem. The problem is the moments when it feels like the easiest answer — when your balance is low, the bill is due, or a purchase feels urgent — and you reach for it without thinking through what it will actually cost you.
Most credit card mistakes are not dramatic. They are small, repeated decisions that accumulate quietly until the interest charges, the CIBIL score damage, and the growing balance suddenly feel very difficult to manage. The good news is that knowing which situations to avoid makes most of this entirely preventable.
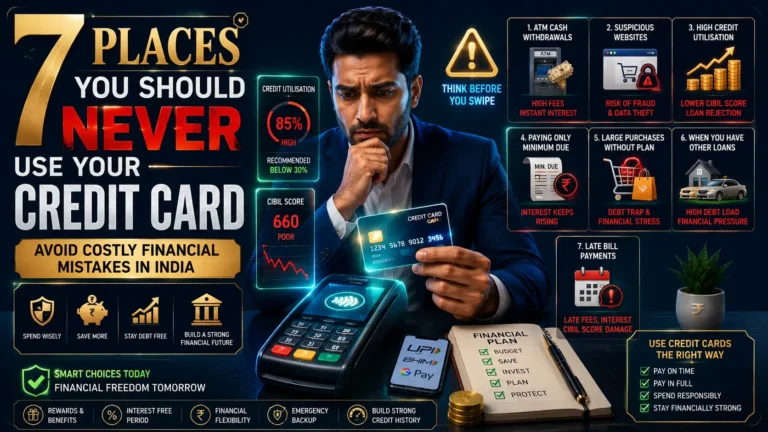
Here are seven situations where financial experts consistently advise keeping the credit card in your pocket.
1. When Your Credit Utilisation Is Already High
This one catches a lot of people off guard because it is not about a single transaction — it is about the ratio.
Your credit utilisation ratio is the percentage of your total credit limit that you are currently using. If your total credit limit across cards is ₹5 lakh and you have already spent ₹4.5 lakh, your utilisation ratio is 90 percent. That is considered extremely poor by credit bureaus.
Financial experts consistently recommend keeping this ratio below 30 percent. So if your limit is ₹5 lakh, try to keep the outstanding balance under ₹1.5 lakh at any given time.
The reason this matters is that credit bureaus like CIBIL look at your utilisation ratio as a signal of how financially stretched you are. Repeatedly spending close to your limit tells them you are dependent on borrowed money, which lowers your CIBIL score and makes it harder to get loan approvals or limit increases in the future.
If you are already near your limit, the right move is to pay down the existing balance before making new purchases — not add to it.
2. ATM Cash Withdrawals
This one has a straightforward rule: never withdraw cash using a credit card unless it is a genuine emergency with no other option.
The reason is that credit cards do not treat cash withdrawals the way they treat regular purchases. There is no grace period. The moment you take money out of an ATM using your credit card, interest starts accruing — from day one — at rates typically between 2.5 and 3 percent per month. That translates to 30 to 36 percent annually, compounded daily.
On top of that, banks charge a cash advance fee of around 2.5 to 3 percent of the withdrawn amount upfront.
So if you withdraw ₹10,000 today, by the end of the month you could owe ₹10,400 or more — even if you pay it back relatively quickly. For larger amounts, this becomes genuinely expensive very fast.
If you need cash, use your debit card, a UPI transfer, or a pre-planned bank transfer instead.
3. When You Cannot Pay the Full Amount This Month
This is one of the most common and costly misunderstandings about credit cards — the idea that paying the “Minimum Due” is a responsible way to manage your balance.
It is not. The minimum due is typically around 5 to 10 percent of your outstanding balance, and paying only that amount does not pause the interest on the rest. Interest continues to accrue daily on the remaining balance at the full rate.
Here is what that looks like in practice. If your credit card bill is ₹50,000 and you pay only the ₹5,000 minimum due, interest continues to build on the remaining ₹45,000 from the payment due date. Over the following weeks and months, that outstanding amount grows — and the interest compounds on itself. People who do this consistently can find themselves paying back significantly more than they originally spent.
The honest advice is simple: if you cannot clear the full balance this month, reconsider whether the purchase makes sense right now. Using a debit card or waiting until you have the funds available costs you nothing extra.
4. Large Purchases Without a Clear Payment Plan
Expensive gadgets, holiday packages, high-end appliances — these are the purchases that feel most tempting to put on a credit card, and the ones that require the most careful thought before you do.
Using a credit card for a large purchase is not automatically a bad idea. Many cards offer zero-cost EMI options or reward points on big transactions, and if you have the funds to repay within the billing cycle, there is no harm at all. The problem is when you make a large purchase hoping to figure out the repayment later.
Financial advisors recommend making large credit card purchases only if you have a specific, realistic plan to repay the amount — either from existing savings or through a structured EMI arrangement. Without that plan, a single large purchase can become the starting point of a debt spiral that takes months or years to exit.
5. Suspicious or Unsecured Websites
Before you enter your card details anywhere online, check two things: the URL and the padlock.
The website address should begin with “https” — the “s” stands for secure and indicates that the connection is encrypted. If it starts with just “http,” your card data is being transmitted without encryption and can be intercepted.
Also check the URL itself carefully. Fraudulent websites often mimic legitimate ones with minor spelling variations or unfamiliar domain names. If something about the website looks slightly off — the design, the URL, the payment page — trust that instinct and find another way to make the purchase.
Sharing card details on an unsecured or suspicious website creates real risk of data theft, fraudulent transactions, and complete account compromise. Use only verified platforms, and consider using a virtual card number — available through many Indian banks — for online transactions you are less certain about.
6. When You Already Have Other Significant Liabilities
If you are currently managing a personal loan, a home loan EMI, or other regular financial obligations, adding credit card expenses on top can push your debt-to-income ratio into uncomfortable territory.
Financial planning generally recommends that total loan and credit obligations should not exceed 40 to 50 percent of your monthly income. When credit card spending is added on top of existing EMIs, crossing that threshold becomes easy — and staying ahead of payments becomes increasingly difficult.
In situations where you are already managing significant liabilities, debit card or UPI transactions are a more disciplined choice. You spend only what you actually have, the money leaves your account immediately, and there is no bill arriving at the end of the month to manage alongside existing obligations.
7. Consistently Late Bill Payments
This last point is about pattern rather than a single situation. If you have a habit of paying your credit card bill after the due date — even by a few days, even occasionally — you are paying for that habit in ways that compound over time.
Late payments trigger immediate late fees from the bank. They also attract interest charges on the full outstanding balance. And they appear on your CIBIL report, where they remain as negative entries that lower your credit score and affect future loan approvals, rental applications, and even some job background checks.
The simplest fix is automation. Set up auto-debit for at least the minimum due amount — though ideally the full balance — so that even if you forget the payment date, the bank deducts it automatically. Set calendar reminders two or three days before the due date as a backup. Missing a payment date is one of the easiest credit mistakes to prevent, and one of the more expensive ones to keep making.
Also Read: How Your Health Insurance Needs Change from 25 to 60
Credit cards are not the problem. Used correctly — with full repayment each month, mindful utilisation, and basic security awareness — they offer genuine benefits. Reward points, purchase protection, the interest-free grace period, and the CIBIL score building that comes with responsible use are all real advantages.
The situations above are simply the ones where the card stops working in your favour and starts working against you. Knowing which situations those are — and having a plan for them — is what separates confident credit card users from people who find themselves managing a growing, increasingly expensive debt.